Project Loan
Term funding for new units, greenfield projects and SME expansion, sized on the project and its promoters.
Which one fits
Terms shown are typical; each lender sets its own.
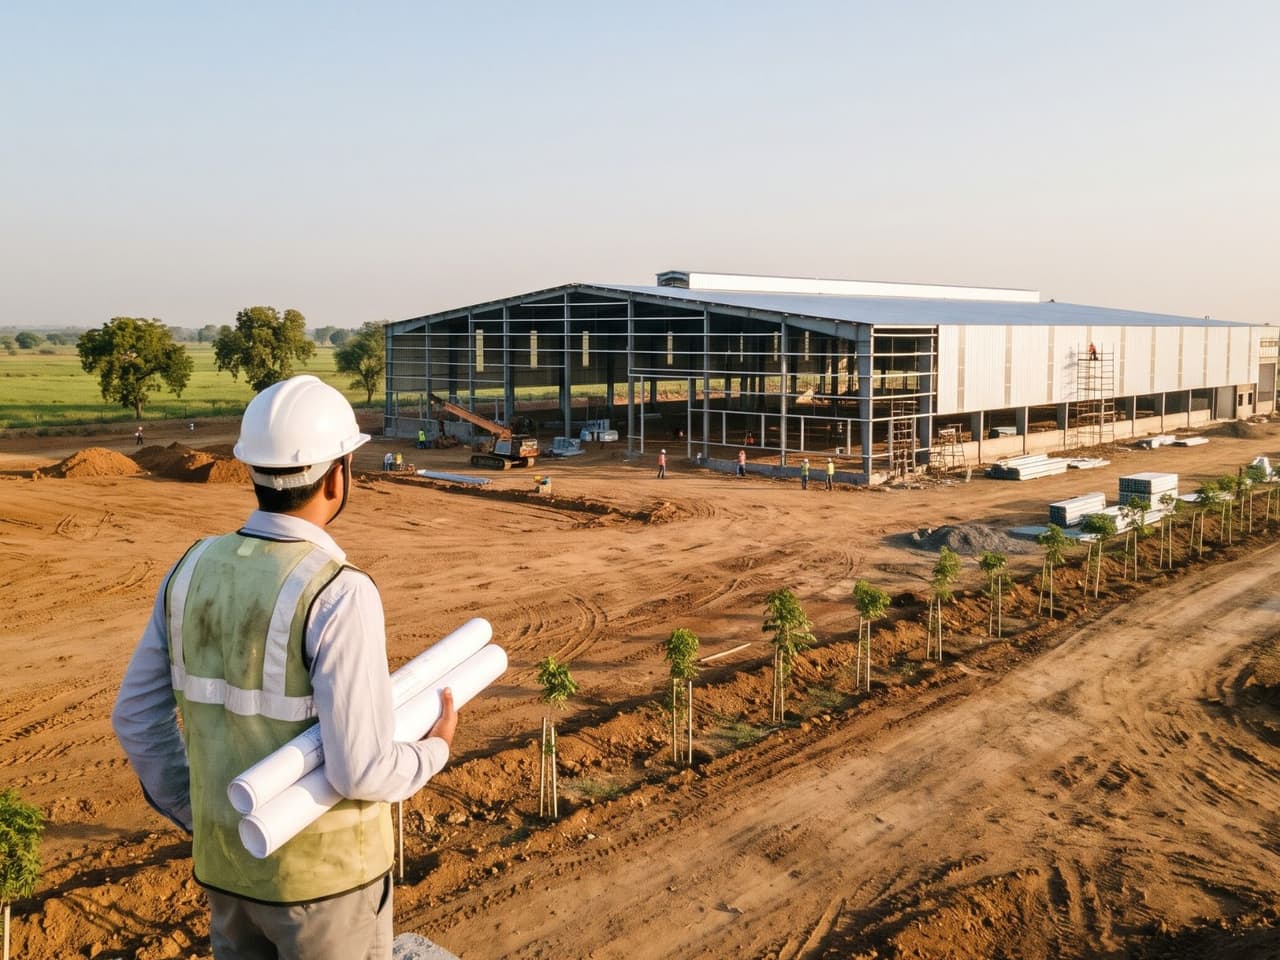
Greenfield
A new unit with no operating history.
- 33% promoter share on new projects
- 8 to 10 years, including up to 18 months' moratorium
- First charge on project assets, with a promoter guarantee
SME funding
Machinery, expansion, modernisation or working capital for a running business.
- Up to 7 years, with a moratorium of up to 6 months
- 33% margin on term loans, 25% on working capital
- Backed by property or liquid securities
Documents to keep ready
Nayaasa is a loan advisor, not a lender. This is what lenders typically ask for, and yours may differ. Approval is the lender's decision.
Applying jointly? Each person gives their own documents. Choose each type in turn.
What to expect
Rules and schemes that apply
Credit guarantee
Micro and small enterprises can be covered by the CGTMSE guarantee up to ₹10 crore.
PMEGP for new units
Project cost up to ₹50 lakh in manufacturing or ₹20 lakh in services, with a 15 to 35% subsidy. The promoter brings in 10%, or 5% in special categories.
STHAPAN from SIDBI
For new units: up to ₹20 crore and up to 75% of cost, with at least 25% from the promoter.
Where RBI's project finance rules apply
When at least 51% of repayment comes from the project's own cash flows: 75% of the land before disbursal outside infrastructure, 50% for PPP infrastructure, and money released by stage.
Who counts as an MSME
By investment and turnover. Micro: ₹2.5 crore and ₹10 crore. Small: ₹25 crore and ₹100 crore. Medium: ₹125 crore and ₹500 crore.
Figures last checked November 2026.
Who it suits
- Promoters setting up a new unit with no operating history
- Small and medium enterprises buying machinery, expanding or modernising
- Firms and companies with a project report, or ready to prepare one
How it works
Tell us about the project
What you are setting up or expanding, the cost and how much you are bringing in.
We read the plan
The project report, the promoters and what lenders will ask of it.
Gather the documents
We give you the list for your case and check each file before it goes to a lender.
The lender assesses
Credit checks, a study of the project and a look at the security.
Sanction and agreement
If the lender agrees, it sets the terms and takes its security.
Disbursement
Money is released on the lender's terms, often by stage of the project.
Common questions
I have no audited accounts yet. Can I still apply?
Yes, for a new unit. Lenders then look at the project report and the promoters instead of a business record.
Is this regulated project finance?
Not always. RBI uses that term only where at least 51% of repayment comes from the project's own cash flows. Many SME term loans do not meet it.
How much must I bring in?
It varies by lender and scheme, commonly a quarter to a third of the project cost.
Does Nayaasa approve the loan?
No. Nayaasa is a loan advisor, not a lender. The final decision and the terms are the lender's.
Other loans we arrange
Let's Build Your Brighter Tomorrow
Get in touch with our advisors for guidance on the loan that fits your plans.